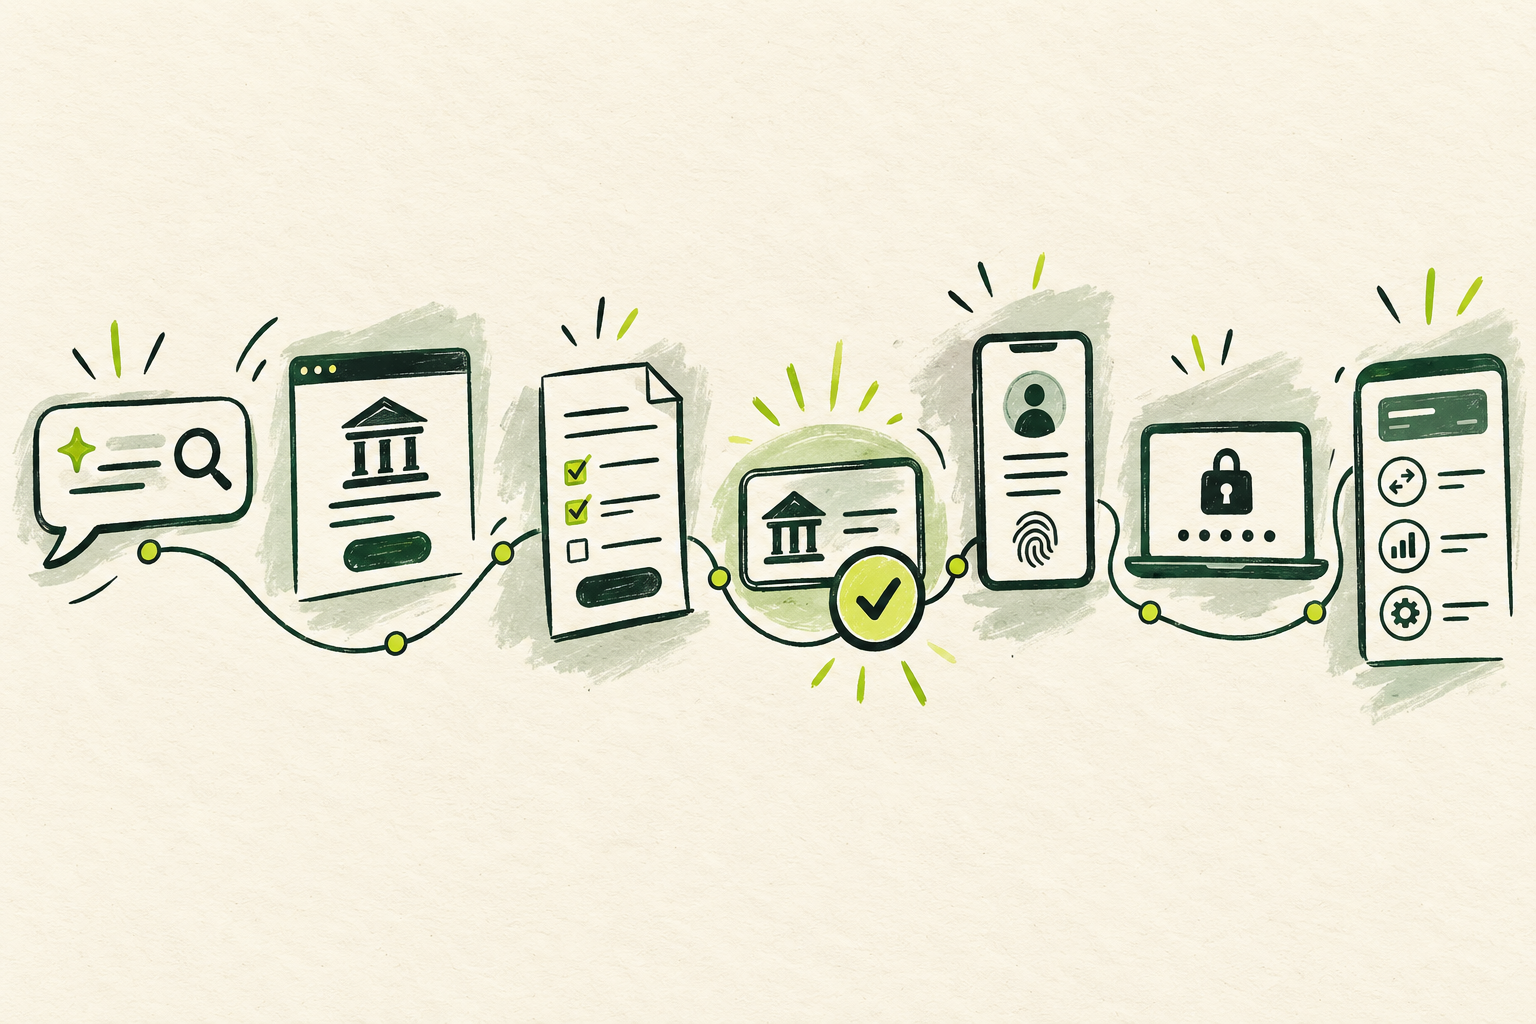
A customer asks an AI assistant which checking accounts offer no monthly maintenance fee and nearby branches.
They follow a recommendation, visit a bank’s website, and start an application. A few days later, they open and fund the account, enroll in digital banking, and log in for the first time.
Eventually, they contact the bank for help.
For the customer, this is one continuous relationship. For the bank, it appears across several systems.
The question is straightforward: Can we connect the AI discovery that brought someone to the bank with the relationship that followed?
We can connect meaningful parts of that journey. The important work is understanding which connections we can observe, which require implementation, and which remain unknown.
Where Adobe Brand Visibility and Semrush fit
Tools such as Adobe Brand Visibility address much of the discovery problem.
Adobe Brand Visibility, formerly Adobe LLM Optimizer, incorporates Semrush intelligence to help organizations understand how their brands appear in AI answers and where they can improve. Its capabilities extend into referral measurement and business-impact reporting through supported analytics integrations. Adobe Brand Visibility ↗
For a bank, this creates several useful questions:
- Are we appearing in answers about relevant banking products?
- Which pages receive citations?
- How are competitors represented?
- Are our products described accurately?
- Which observable AI referrals lead to meaningful website activity?
That is a valuable starting point. But brand visibility and customer identity are different kinds of information.
Knowing the question does not mean knowing the customer
Semrush uses different collection methods across its reports. Its prompt research incorporates clickstream-derived data and modeled topic demand, while custom Prompt Tracking queries selected prompts on supported platforms. Semrush data methodology ↗
Those capabilities help a bank understand the questions surrounding its products.
They do not, by themselves, establish that a particular customer asked a particular private question.
For example, a tool might show that a bank appears for:
Example prompt“Which checking accounts have no monthly maintenance fee?”
Separately, the bank might observe an AI referral to its checking-account page.
Those observations are related in subject matter. They are not enough to prove that the visitor asked that exact question or saw the monitored answer.
The remaining gap is the connection between an individual AI conversation and an identifiable banking customer.
The documentation reviewed does not establish a general customer-level link of that kind.
The observable journey begins at arrival
Once someone lands on the bank’s website, the measurement opportunity becomes more concrete.
Adobe’s Referral Traffic documentation describes traffic insights built from CDN logs, with supported analytics integrations for business-impact reporting. CJA can also populate that reporting when enabled for the organization. Adobe referral reporting ↗
At this stage, preserve the information available through permitted collection:
- Referral source, when present.
- Landing page and arrival time.
- Approved campaign parameters.
- First-party visitor or session identifiers.
- Applicable consent and collection state.
Separate human visits from crawler and agent requests. They represent different activity.
Also keep an unknown-source category. A customer might read an AI answer, close it, and type the bank’s address into a browser later. That visit may carry no observable evidence of the earlier AI interaction.
A missing referral should remain missing—not be reconstructed from a guess.
Connect the application before connecting the entire relationship
The next useful connection happens when the visitor starts an application.
This is where identifier design matters:
| Identifier | What it helps connect |
|---|---|
| Visitor identifier | Eligible activity within an observable browser context |
| Application identifier | Steps and outcomes for one application |
| Customer identifier | Known customer activity across configured systems |
| Account identifier | Milestones and activity for a particular account |
These identifiers are related, but they are not interchangeable.
One customer may submit multiple applications. One joint account may involve two people. A visitor may switch devices before becoming identifiable.
Build governed mappings at supported transition points. A later login should not be assumed to resolve every earlier anonymous visit.
The goal is a defensible connection between the observed arrival, the relevant application, and its eventual outcome.
Follow what happens after account opening
Account opening is an important milestone. It is not the end of the journey.
For a banking measurement model, I would separate:
- Application started.
- Application submitted.
- Account opened.
- Account funded.
- Digital enrollment completed.
- Successful login.
- Relevant account-use milestones.
- Service interaction and resolution.
Use authoritative operational sources for account opening and funding. A confirmation-page view alone may not establish the final business outcome.
For enrollment and servicing, collect the context needed for analysis without copying credentials, authentication secrets, or unrestricted service transcripts into analytics.
AEP and CJA can support the connected analysis, but the datasets and identity configuration need deliberate implementation. Loading data into the platform does not automatically create the intended customer journey. Adobe connection configuration ↗
The resulting questionAmong customers with a linked, observed AI referral, how many funded an account, enrolled digitally, and continued using the relationship?
Build a connected view without overstating the evidence
I would organize reporting into four complementary views:
| View | What it answers |
|---|---|
| AI visibility | Where does the bank appear within the tool’s monitored coverage? |
| Referral performance | Which observable AI visits reach the site and begin applications? |
| Customer outcomes | Which linked applications become funded, enrolled, active relationships? |
| Measurement coverage | Where are referral information or identity connections missing? |
These views can reveal useful patterns.
Perhaps checking-account citations increase, identifiable AI referrals rise, and more funded accounts become associated with those visits.
That is evidence worth investigating. It does not prove which private prompt produced each account or that the citation increase caused the improvement.
Keep the distinction visible in the reporting language.
“Funded accounts associated with an observed AI referral” is a defensible description when the linkage supports it.
“Accounts caused by AI recommendations” requires stronger evidence.
Measure the relationship, not just the visit
The most useful metrics extend beyond traffic:
- Application starts following an observed AI referral.
- Funded accounts linked to those applications.
- Digital enrollment within a defined period after opening.
- Subsequent account activity.
- Service-contact and resolution patterns.
- The percentage of journeys with reliable identity linkage.
Define the attribution rule too. If someone first arrives through AI and later returns through paid search, the report should explain how those touchpoints receive credit.
Use consistent observation windows so recent customers are not compared unfairly with customers who have had months to enroll and become active.
A practical starting checklist
Connect what you can observe.
- Configure the available visibility, referral, and analytics integrations.
- Separate monitored prompts, agent requests, and human visits.
- Preserve permitted arrival and referral information.
- Map visitor, application, customer, and account identifiers.
- Confirm business outcomes through authoritative systems.
- Connect enrollment and service milestones.
- Report unknown sources and unresolved identity links.
- Define attribution rules, observation windows, and data freshness.
The opportunity is to understand how observable AI discovery contributes to a banking relationship.
Adobe Brand Visibility and Semrush help explain how the bank appears before the visit. AEP, CJA, and the bank’s operational data help explain what happens afterward.
The strongest measurement connects the evidence it has—and makes the remaining gaps clear.